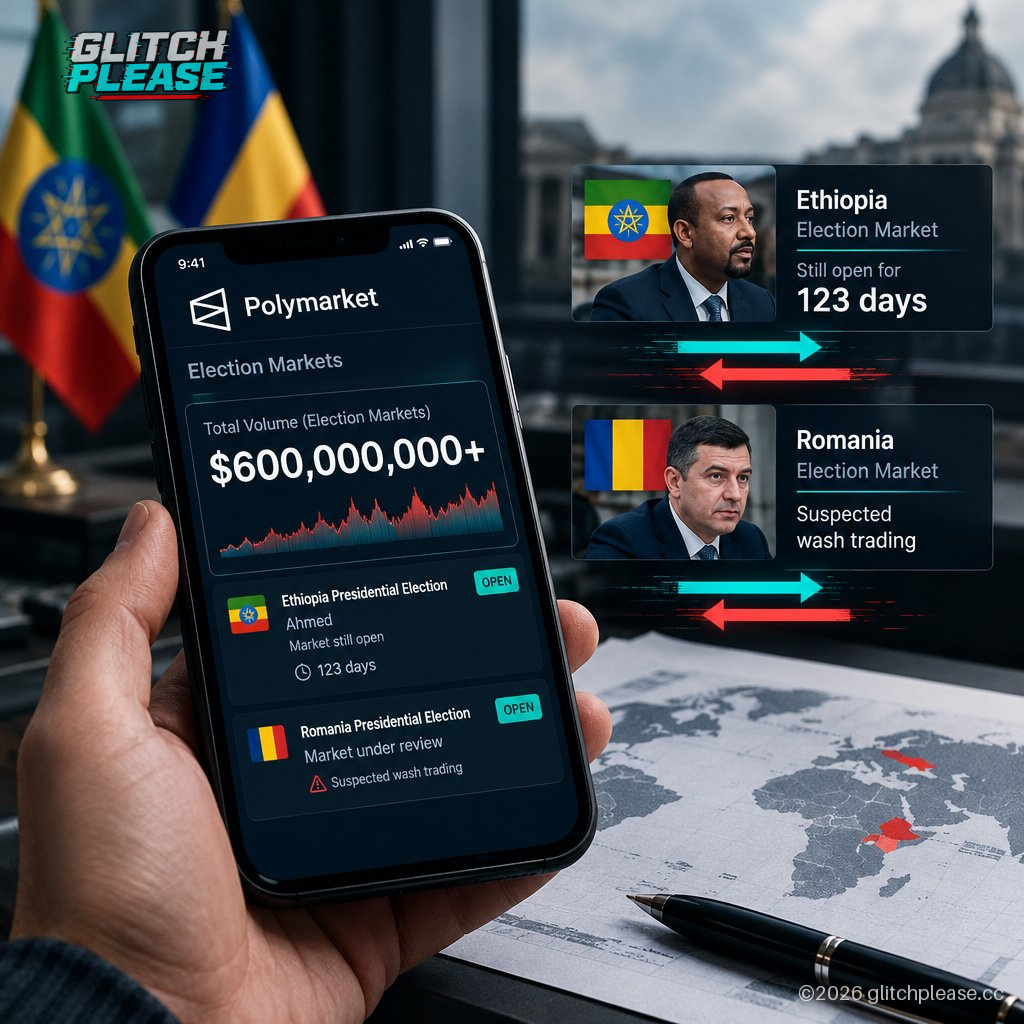
Polymarket’s election markets saw $600 million in trades after the outcomes were effectively settled, according to Ars Technica’s reporting. Some markets stayed open for months, and researchers identified trading patterns they say were consistent with wash trading. The election may have been over; the market, apparently, had not received the memo.
One example involved Ethiopia. Polymarket’s rules said the market would resolve in October, after the prime minister was formally appointed and sworn in. That left it open for 123 days after Ahmed’s victory was all but a foregone conclusion. During that stretch, bursts of apparently irrational trading continued. Users asked “THIS NOT RESOLVED?” and, with less patience, “fuckkkk.”
Polymarket head of global intelligence and investigations Shana Bautista told WIRED the company “immediately flagged this activity, investigated, and blocked the accounts from trading.” But Polymarket did not answer follow-up questions about why those accounts were able to generate so much volume before the company intervened. Blocking accounts is a response; how they got that far is the more interesting question.
Researchers also found suspicious activity around a 2024 election market in Romania. The initial election was called off amid fears of foreign interference, and a new race took place several months later. Polymarket kept the original market open alongside the new one. It was there that Sethi and colleagues noticed trading patterns their algorithm flagged as potential wash trading.
Wash trading involves accounts repeatedly buying and selling to create the appearance of heavy activity, while money moves back and forth between them. Sethi said that, during certain weeks, “99.6 percent of volume in this market” was wash trading. That is an assessment of the flagged volume, not proof that every trade in the market was manipulated. Still, it is a remarkable number for a platform whose markets are meant to aggregate what people believe will happen.
The practice is banned on regulated US financial exchanges and specifically prohibited under Polymarket’s terms of service. An earlier study by Sethi and colleagues also found evidence of widespread wash trading on Polymarket’s offshore platform. The distinction matters: suspected activity identified by researchers is not the same as a regulator’s finding, and the available reporting does not establish who was behind the accounts or why they traded.
There is a genuine rules problem here, too. Polymarket’s Ethiopia market was designed to resolve only after a formal appointment and swearing-in, not simply when the outcome seemed obvious. That may explain why it remained open, but a market can be technically unresolved while being practically settled. Sethi calls these “zombie markets”: contracts still available to trade after the event has already happened or is no longer happening.
Prediction markets depend on users believing that prices reflect meaningful activity. Keeping stale markets alive invites confusion; letting suspicious volume pile up before blocking accounts invites harder questions. The elections ended. The trades kept coming. That’s not exactly a vote of confidence.
Sources: Glitch Please! and Ars Technica — https://arstechnica.com/tech-policy/2026/10/polymarket-saw-600-million-in-election-trades-after-the-elections-were-over/ — Reporting on Polymarket election-market trading, researcher Sethi’s findings, and comments provided by Polymarket to WIRED.
Generated by AI
